The Hybrid Bonding Industry is entering a new phase of growth as semiconductor manufacturers increasingly adopt advanced packaging technologies to overcome the physical and economic limitations of conventional chip scaling. The growing demand for artificial intelligence (AI), high-performance computing (HPC), high-bandwidth memory (HBM), chiplets, and 3D integrated circuits is creating strong demand for high-density and ultra-fine-pitch interconnect technologies.
According to MarketsandMarkets, the global Hybrid Bonding Market was valued at USD 164.7 million in 2025 and is projected to reach USD 633.9 million by 2032, registering a CAGR of 21.2% from 2025 to 2032. The market is being driven by the semiconductor industry’s transition toward 3D integration, which enables higher bandwidth, lower power consumption, lower latency, and greater interconnect density.
Hybrid bonding combines dielectric-to-dielectric bonding with metal-to-metal interconnections, particularly copper-to-copper bonding. This approach enables much finer interconnect pitches than conventional bump-based packaging and is becoming increasingly important for next-generation logic, memory, chiplet, CMOS image sensor (CIS), and heterogeneous integration applications.
Top 10 Key Takeaways
- The global Hybrid Bonding Market was valued at USD 164.7 million in 2025.
- The market is projected to reach USD 633.9 million by 2032, registering a 21.2% CAGR from 2025 to 2032.
- AI, HPC, chiplets, HBM, and 3D integration are major forces accelerating hybrid bonding adoption.
- Die-to-die (D2D) hybrid bonding is projected to register a 35.3% CAGR from 2025 to 2032.
- Wafer bonders are expected to register the highest CAGR among equipment types.
- Copper-to-copper bonding is expected to lead the bonding-type segment and register the fastest growth.
- The computing and logic segment is expected to grow at a 26.0% CAGR from 2025 to 2032.
- Asia Pacific accounted for 51.6% of market revenue in 2024 and is expected to remain the fastest-growing regional market.
- The IT and telecommunications vertical is expected to hold the largest market share in 2025.
- High capital requirements, stringent surface-quality requirements, ultra-low defectivity, and process standardization remain important industry challenges.
Download PDF Brochure @ https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=2641237
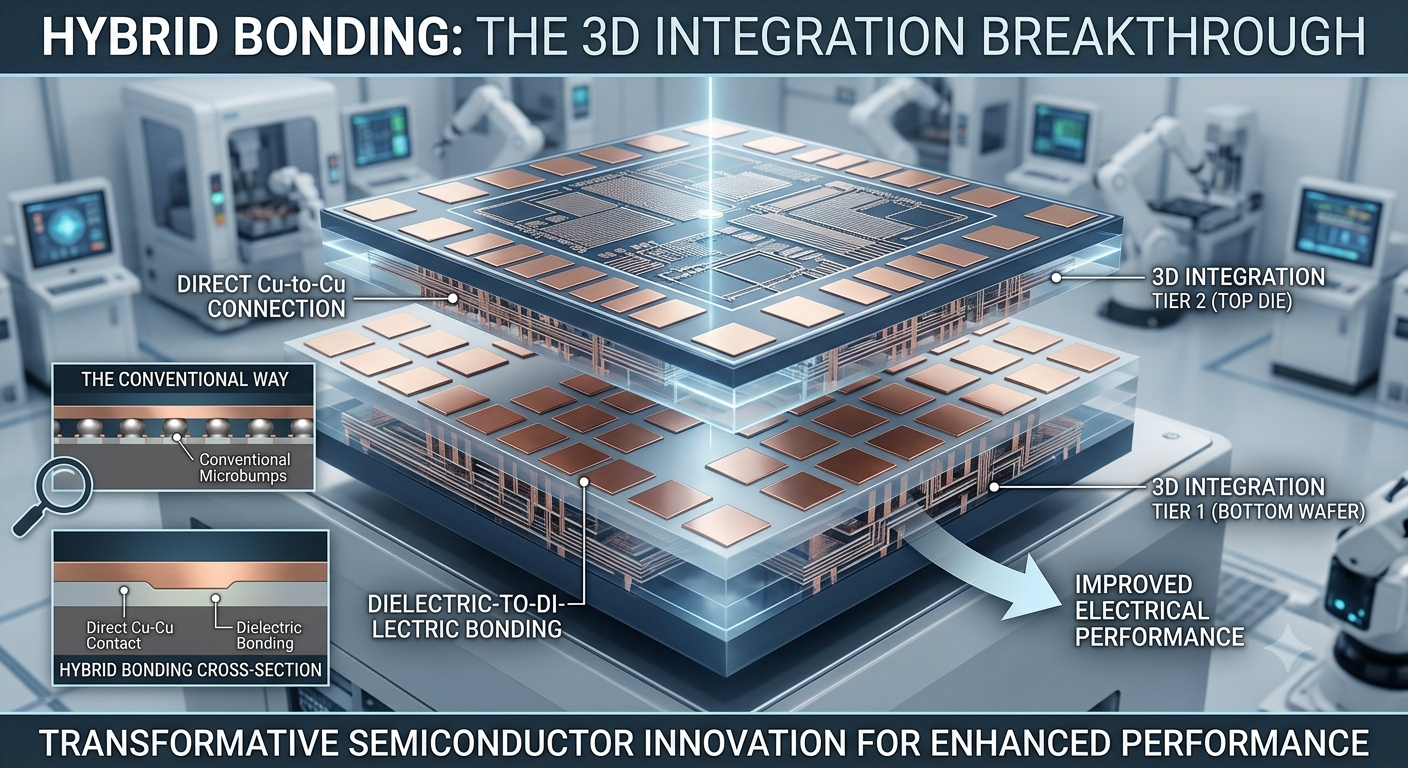
Hybrid Bonding Industry Statistics and Market Growth
The Hybrid Bonding Industry statistics demonstrate the accelerating adoption of advanced semiconductor packaging. The market is expected to expand from USD 164.7 million in 2025 to USD 633.9 million by 2032, representing a 21.2% CAGR.
This growth reflects the increasing importance of advanced packaging as traditional transistor scaling becomes more difficult and expensive. Instead of relying solely on smaller process nodes, semiconductor manufacturers are combining multiple dies, chiplets, and memory components into increasingly sophisticated architectures.
Hybrid bonding enables direct connections between wafers or dies and provides high-density vertical interconnects. These capabilities are particularly relevant for AI accelerators, HPC processors, memory systems, and advanced logic devices that require rapid movement of large volumes of data.
The technology is also being supported by investments from foundries and integrated device manufacturers (IDMs) in advanced packaging infrastructure. Improvements in wafer bonding equipment, surface preparation, alignment, cleaning, chemical mechanical planarization (CMP), and inspection technologies are helping improve manufacturing readiness.
AI and HPC Accelerate Hybrid Bonding Adoption
AI and HPC are among the most important forces shaping the Hybrid Bonding Industry. Modern AI processors and accelerators require extremely high bandwidth and low-latency communication between processing and memory components.
Conventional interconnect technologies can become a bottleneck as processor performance increases. Hybrid bonding addresses this requirement by enabling ultra-fine-pitch interconnects and tightly integrated 3D architectures.
AI accelerators, GPUs, advanced processors, and memory technologies increasingly require higher integration density while maintaining power efficiency. Hybrid bonding can reduce interconnect length and parasitic effects, supporting faster data transfer and improved system-level performance.
The increasing deployment of AI infrastructure and data centers is therefore encouraging semiconductor manufacturers to invest in advanced packaging technologies capable of supporting next-generation computing architectures. MarketsandMarkets identifies the growth of AI, HPC, and logic-memory applications as a key driver for hybrid bonding adoption.
Chiplets and 3D Integration Transform Semiconductor Packaging
The shift toward chiplet architectures is another major factor supporting market expansion. Chiplets allow semiconductor designers to divide complex systems into multiple smaller dies and integrate them within a single package.
Hybrid bonding is well suited to this architecture because it supports high-density die-to-die and wafer-to-die connections. This can enable designers to combine different process technologies, functions, and components within a single package.
As semiconductor architectures become increasingly heterogeneous, advanced packaging is becoming an important part of system design. Hybrid bonding supports this transition by enabling compact vertical connections between different dies.
MarketsandMarkets reports that die-to-die (D2D) hybrid bonding is expected to register a CAGR of 35.3% between 2025 and 2032, highlighting the growing importance of chiplet-based and multi-die architectures.
Copper-to-Copper Bonding Gains Importance
Copper-to-copper (Cu-Cu) bonding is becoming an important technology within the Hybrid Bonding Industry. Direct copper connections can provide high electrical performance and enable very fine interconnect pitches.
Cu-Cu bonding is expected to lead the market and register the fastest growth among bonding types during the forecast period. Its ability to support high-density connections makes it suitable for advanced logic, memory, AI processors, and 3D stacked devices.
Compared with conventional solder-based interconnects, copper-to-copper hybrid bonding can enable shorter electrical paths and lower parasitic effects. These characteristics become increasingly important as chip designers seek higher bandwidth and lower power consumption.
Wafer Bonders Drive Equipment Demand
The equipment ecosystem is a critical part of the Hybrid Bonding Industry. Semiconductor manufacturers require specialized wafer bonders, surface preparation tools, cleaning and CMP systems, and inspection and metrology equipment to achieve reliable hybrid bonding.
According to MarketsandMarkets, the wafer bonders segment is expected to register the highest CAGR from 2025 to 2032. As fabs increase their 3D integration capacity, wafer bonders are becoming foundational equipment within advanced packaging lines.
The increasing complexity of hybrid bonding processes is also creating opportunities for equipment suppliers to develop integrated platforms. These systems can combine bonding, alignment, surface preparation, inspection, and process control capabilities to improve manufacturing efficiency.
High-precision equipment is particularly important because hybrid bonding requires extremely accurate alignment and exceptionally clean surfaces. Even small particles, surface defects, or alignment errors can affect bond quality and manufacturing yield.
Heterogeneous Integration Creates New Opportunities
Heterogeneous integration is becoming increasingly important as semiconductor manufacturers combine different chip technologies and functions within a single package.
MarketsandMarkets expects the heterogeneous integration devices segment to exhibit the fastest growth rate during the forecast period. Hybrid bonding can support this trend by enabling dense connections between different dies and components.
The technology is particularly relevant to applications that require logic, memory, sensing, and connectivity components to operate closely together. This approach can help designers optimize system performance without requiring every component to be manufactured using the same process technology.
The growth of heterogeneous integration is therefore expanding the role of hybrid bonding beyond traditional wafer stacking toward more flexible multi-die architectures.
Computing and Logic Applications Expand Rapidly
The computing and logic segment is expected to grow at a CAGR of 26.0% from 2025 to 2032. This growth is supported by increasing demand for AI accelerators, HPC processors, data center chips, and advanced computing architectures.
Computing and logic applications require high bandwidth, low latency, and efficient communication between processing and memory components. Hybrid bonding can provide the fine-pitch vertical connections needed to address these requirements.
As AI workloads become more computationally intensive, processor and memory architectures are evolving toward greater integration. This creates opportunities for hybrid bonding equipment and process technologies across advanced logic and memory packaging.
Memory and HBM Support Market Development
High-bandwidth memory is another important technology influencing the Hybrid Bonding Industry. AI and HPC systems require large amounts of high-speed memory to support increasingly complex workloads.
Hybrid bonding can enable tighter integration between memory and logic components, reducing the physical distance data must travel between processing and memory devices.
MarketsandMarkets identifies HBM and advanced memory stacking among the trends expanding hybrid bonding into new application areas. The technology is also increasingly relevant for high-layer-count 3D memory architectures.
CMOS Image Sensors Create Additional Applications
Hybrid bonding is also gaining attention in CMOS image sensors (CIS) and other sensing applications. Stacking sensor components can enable higher pixel density and improve device performance while maintaining compact form factors.
MarketsandMarkets identifies deployment of hybrid bonding in CIS and AR/VR sensors as an opportunity because of its potential to improve signal-to-noise ratio and pixel density.
The growth of advanced cameras, machine vision, automotive sensing, AR/VR devices, and imaging systems could therefore create additional opportunities for hybrid bonding technologies beyond computing and memory.
Asia Pacific Leads the Hybrid Bonding Ecosystem
Asia Pacific represents a major center for semiconductor manufacturing and advanced packaging, making it a critical region for the Hybrid Bonding Industry.
The region accounted for 51.6% of hybrid bonding market revenue in 2024 and is expected to remain the fastest-growing regional market during the forecast period.
The strong position of Asia Pacific is supported by its concentration of semiconductor foundries, IDMs, memory manufacturers, equipment suppliers, and advanced packaging facilities. Taiwan, South Korea, China, and Japan are particularly important contributors to the regional semiconductor ecosystem.
Government initiatives, semiconductor investments, manufacturing capacity expansion, and continued demand for advanced chips are supporting regional adoption of hybrid bonding.
IT and Telecommunications Remain a Major Vertical
The IT and telecommunications vertical is expected to hold the largest market share in 2025. Demand for high-performance processors, data center infrastructure, communication equipment, and advanced memory technologies is supporting the adoption of high-density packaging solutions.
AI-driven workloads and cloud computing are increasing requirements for processor performance and data throughput. Hybrid bonding can support these requirements by enabling more efficient chip integration and shorter interconnect paths.
Beyond IT and telecommunications, hybrid bonding has applications across consumer electronics, automotive, aerospace and defense, healthcare, and industrial automation.
Front-End and Back-End Process Developments
Hybrid bonding involves multiple process stages, including wafer preparation, surface activation, alignment, bonding, cleaning, CMP, and inspection.
The back-end process flow is expected to dominate the market during the forecast period. Advanced packaging operations increasingly require high levels of precision to maintain bond quality and manufacturing yield.
Surface preparation is particularly important because hybrid bonding requires highly planarized and contamination-free surfaces. Manufacturers must control surface roughness, particles, alignment, and bond interfaces with high precision.
Inspection and metrology therefore play a critical role in identifying defects and maintaining process consistency.
Advanced Equipment and Process Automation
Automation is becoming an important technology trend within the Hybrid Bonding Industry. High-volume semiconductor manufacturing requires repeatable processes, accurate alignment, low defect rates, and high equipment utilization.
Equipment manufacturers are developing solutions that integrate process monitoring, automated wafer handling, precision alignment, surface preparation, and inspection.
Process automation can help semiconductor manufacturers improve throughput and maintain consistent bonding quality. As hybrid bonding moves toward higher-volume production, automation and advanced process control are expected to become increasingly important.
Recent Industry Developments
Technology and equipment suppliers are continuing to strengthen the hybrid bonding ecosystem.
In May 2025, SUSS MicroTec introduced the XBC300 Gen2 D2W platform, expanding its hybrid bonding portfolio with a die-to-wafer solution supporting 200 mm and 300 mm substrates.
In April 2025, Applied Materials acquired a 9% stake in BE Semiconductor Industries (Besi), strengthening their collaboration around hybrid bonding equipment for advanced chip packaging. The companies have been working on die-based hybrid bonding solutions designed to create direct copper-to-copper connections between chiplets.
In December 2024, Tokyo Electron introduced the Ulucus LX, an extreme laser lift-off system for 300 mm wafer-bonded devices, integrating laser irradiation, wafer separation, and wafer cleaning capabilities.
These developments demonstrate the industry’s focus on improving bonding precision, process integration, automation, and manufacturing scalability.
Key Companies in the Hybrid Bonding Industry
The competitive landscape includes equipment manufacturers and technology providers supporting wafer bonding, surface preparation, metrology, cleaning, CMP, and advanced packaging.
Major companies identified by MarketsandMarkets include EV Group (EVG), Applied Materials, SUSS MicroTec, Besi, Kulicke & Soffa Industries, Tokyo Electron, ASMPT, Lam Research, SHIBAURA MECHATRONICS, Hanmi Semiconductor, Onto Innovation, DISCO, TORAY ENGINEERING, KLA, and Beijing U-Precision Tech.
EV Group, SUSS MicroTec, and Applied Materials are identified as prominent players based on their market presence and product portfolios. MarketsandMarkets also identifies SET Corporation, Beijing U-Precision Tech, and Applied Microengineering among startups and SMEs with specialized positions in the ecosystem.
Challenges Facing the Hybrid Bonding Industry
Despite its growth potential, hybrid bonding involves significant technical and economic challenges.
One major restraint is substantial upfront capital investment. Semiconductor manufacturers need expensive equipment for wafer bonding, cleaning, metrology, surface preparation, and alignment. These costs can create barriers for smaller manufacturers and new market entrants.
Another challenge is maintaining ultra-low defectivity across wafers. Hybrid bonding requires extremely clean surfaces and precise alignment. Particles, contamination, surface irregularities, and alignment errors can affect bond quality and yield.
The industry also faces a lack of standardization in die formats, pad structures, and surface pre-treatment processes. Greater standardization could support interoperability and broader adoption across semiconductor manufacturing ecosystems.
Future Outlook for the Hybrid Bonding Industry
The future of the Hybrid Bonding Industry is closely linked to the evolution of AI computing, chiplets, HBM, 3D integrated circuits, and heterogeneous integration.
As conventional scaling becomes increasingly challenging, semiconductor companies are placing greater emphasis on advanced packaging as a pathway to improve system-level performance. Hybrid bonding provides a mechanism for achieving ultra-fine-pitch interconnects and dense vertical integration.
The market’s projected increase from USD 164.7 million in 2025 to USD 633.9 million by 2032, at a 21.2% CAGR, reflects the growing role of hybrid bonding in next-generation semiconductor architectures.
Future developments are likely to focus on higher bonding accuracy, lower defectivity, greater throughput, improved surface preparation, advanced metrology, automated process control, and scalable die-to-wafer and die-to-die manufacturing.
As AI and HPC systems demand greater processing performance and memory bandwidth, hybrid bonding is positioned as an important technology within the broader advanced semiconductor packaging ecosystem.
Frequently Asked Questions
1. What is the size of the Hybrid Bonding Industry in 2025?
The global Hybrid Bonding Market was valued at USD 164.7 million in 2025.
2. What will be the Hybrid Bonding Market size by 2032?
The market is projected to reach USD 633.9 million by 2032, growing at a CAGR of 21.2% from 2025 to 2032.
3. Which hybrid bonding architecture is expected to grow fastest?
The die-to-die (D2D) segment is expected to register the fastest growth, with a projected 35.3% CAGR from 2025 to 2032.
4. Which region is expected to be the fastest-growing hybrid bonding market?
Asia Pacific is expected to be the fastest-growing regional market and accounted for 51.6% of market revenue in 2024.
5. Who are the key companies in the Hybrid Bonding Industry?
Key companies include EV Group, Applied Materials, SUSS MicroTec, Besi, Kulicke & Soffa Industries, Tokyo Electron, ASMPT, Lam Research, SHIBAURA MECHATRONICS, Hanmi Semiconductor, Onto Innovation, DISCO, TORAY ENGINEERING, KLA, and Beijing U-Precision Tech.
The Hybrid Bonding Industry is becoming an increasingly important part of advanced semiconductor packaging as chipmakers move toward 3D integration, chiplets, HBM, and heterogeneous architectures. The technology’s ability to provide ultra-fine-pitch, high-density interconnects makes it relevant to AI, HPC, advanced logic, memory, CIS, and next-generation computing systems.
With the market projected to reach USD 633.9 million by 2032 from USD 164.7 million in 2025, hybrid bonding is entering a period of significant expansion. Continued investment in wafer bonders, surface preparation, metrology, cleaning, CMP, and process automation will be important for scaling the technology to high-volume manufacturing.
The combination of AI-driven computing demand, chiplet adoption, advanced memory architectures, and increasing semiconductor packaging investments is expected to remain central to the evolution of the Hybrid Bonding Industry through 2032.
