AI Infrastructure, Cloud Computing, and High-Performance Processing Drive Market Expansion
The global data center chip industry is experiencing rapid growth as organizations increasingly invest in artificial intelligence (AI), cloud computing, machine learning, and high-performance computing infrastructure. The growing adoption of generative AI applications, large language models (LLMs), and data-intensive workloads is creating significant demand for advanced processors, graphics processing units (GPUs), memory chips, and specialized AI accelerators.
According to MarketsandMarkets, the global data center chip market is projected to grow from USD 283.16 billion in 2026 to USD 687.65 billion by 2032, registering a compound annual growth rate (CAGR) of 15.9% during 2026–2032. Increasing investments in hyperscale data centers, rising demand for energy-efficient computing, and the expansion of AI-driven applications are among the major factors supporting market growth.
The evolving Data Center Chip Market Trends indicate that semiconductor innovation, advanced processing architectures, and growing investments in AI infrastructure will play an important role in shaping the industry’s future.
Rising AI Workloads Accelerate Demand for GPUs and AI Accelerators
One of the most significant Data Center Chip Market Trends is the increasing deployment of GPUs and specialized AI accelerators to support complex computing workloads. Unlike traditional processors, GPUs are designed to handle parallel processing tasks efficiently, making them suitable for AI model training, deep learning, data analytics, and generative AI applications.
The growing use of large language models and generative AI platforms is increasing demand for high-performance computing infrastructure. Hyperscale cloud providers and enterprise organizations are investing in advanced GPU-based servers to improve processing capabilities, reduce computation time, and support large-scale AI deployments.
Specialized AI accelerators are also gaining traction because they are designed to optimize specific machine learning and inference workloads. These chips help data center operators improve computational efficiency while addressing the growing performance requirements of modern AI applications.
Hyperscale Data Center Expansion Supports Market Growth
The rapid expansion of hyperscale data centers is another important factor influencing Data Center Chip Market Trends. Cloud service providers are continuously expanding their infrastructure to accommodate increasing demand for cloud storage, enterprise applications, AI computing, and digital services.
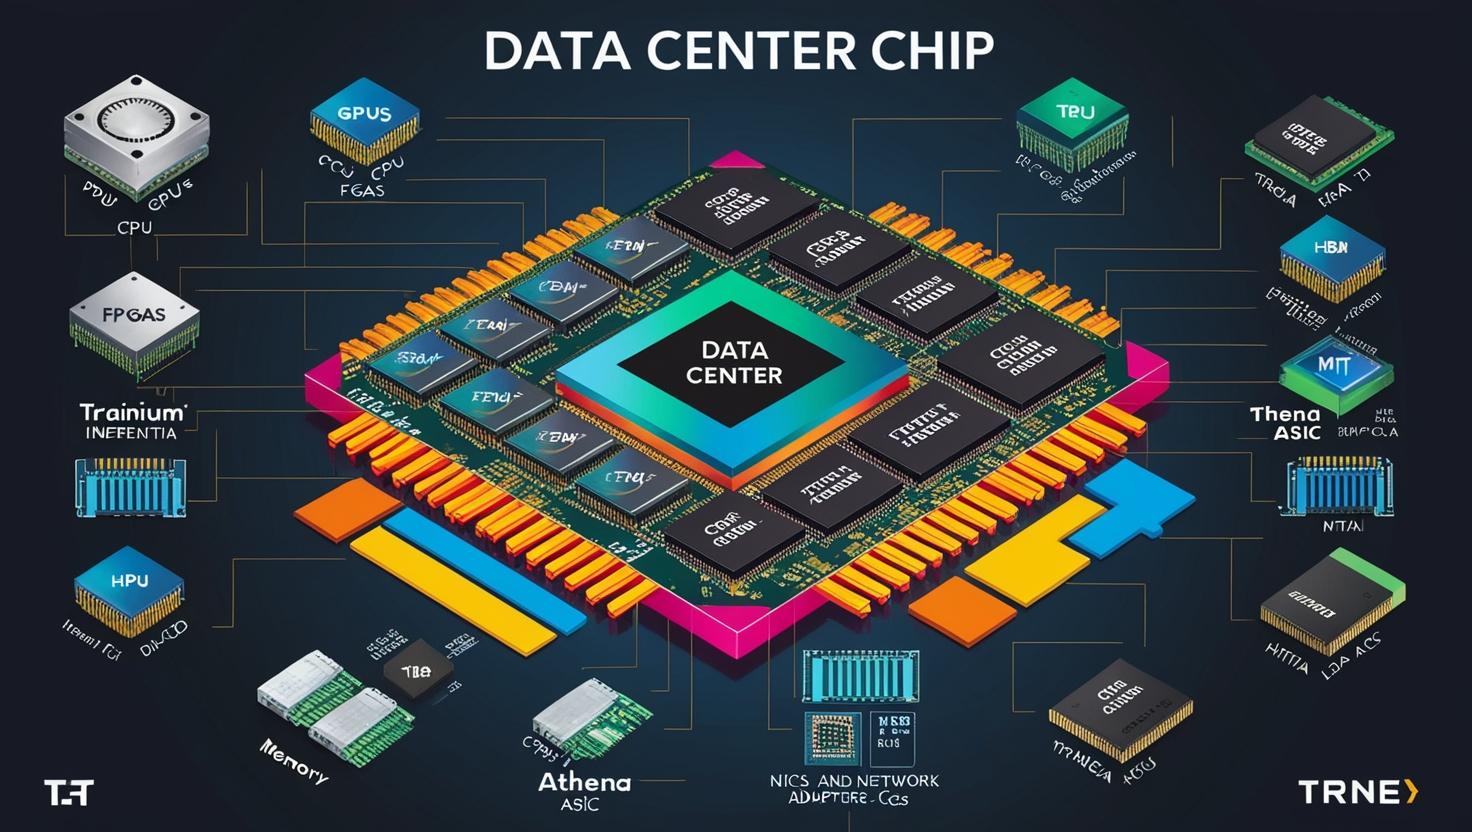
Large data centers require advanced CPUs, GPUs, memory components, and networking chips to manage substantial volumes of information and complex computing operations.
The expansion of hyperscale infrastructure is encouraging semiconductor manufacturers to develop next-generation chips offering higher processing performance, improved scalability, and better energy efficiency.
Additionally, investments in high-speed connectivity and advanced server architectures are increasing demand for specialized semiconductor components across modern data center environments.
Growing Adoption of High-Bandwidth Memory and Advanced Semiconductor Technologies
Memory technology is becoming increasingly important as AI applications require faster access to large volumes of data. High-bandwidth memory (HBM) is gaining importance in AI servers and GPU-based computing systems because it supports high data-transfer rates and improves processing efficiency.
According to MarketsandMarkets, the memory segment is expected to register the highest CAGR of 16.7% during the forecast period.
The increasing complexity of AI models and the growing size of training datasets are encouraging manufacturers to invest in advanced memory technologies. HBM, high-speed memory interfaces, and innovative chip packaging solutions are becoming important components of next-generation data center infrastructure.
These developments are creating new opportunities for semiconductor manufacturers specializing in memory chips, advanced packaging, and high-performance computing components.
Download PDF Brochure @ https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=39999570
Custom AI Chips and FPGA Accelerators Create New Opportunities
Another emerging development shaping Data Center Chip Market Trends is the growing adoption of custom-designed processors and field-programmable gate arrays (FPGAs).
Cloud service providers and large enterprises are increasingly exploring customized chips to optimize computing performance for specific workloads. Application-specific integrated circuits (ASICs) and FPGAs can help organizations improve processing efficiency, reduce latency, and optimize power consumption for selected AI and data processing applications.
Custom AI accelerators are also enabling technology companies to reduce dependence on general-purpose processors for specialized computing requirements.
The growing adoption of customized semiconductor architectures is expected to create opportunities for chip developers and data center technology providers.
Energy Efficiency Becomes a Critical Market Priority
Although demand for advanced data center chips continues to increase, energy consumption remains a major industry challenge. AI training and inference workloads require substantial computing resources, increasing electricity consumption and cooling requirements across data center facilities.
As a result, manufacturers are prioritizing the development of energy-efficient processors, optimized chip architectures, and advanced power management technologies.
Innovations in semiconductor design are helping data center operators improve performance per watt while managing operational costs. Efficient memory systems, advanced packaging, and optimized computing architectures are also supporting efforts to reduce energy requirements.
The growing emphasis on sustainable digital infrastructure is expected to influence future Data Center Chip Market Trends and product development strategies.
Cloud Service Providers Lead Data Center Chip Adoption
Cloud service providers represent a major end-user segment in the global data center chip market. Companies operating large cloud infrastructure platforms require high-performance semiconductor solutions to support enterprise computing, AI services, data storage, and large-scale digital applications.
The increasing adoption of cloud-based AI platforms is encouraging providers to invest in advanced CPUs, GPUs, memory technologies, and networking components.
Technology companies are also developing proprietary processors and AI accelerators to improve infrastructure performance and optimize operating costs.
As businesses increasingly migrate workloads to cloud environments, demand for scalable and energy-efficient data center chips is expected to remain strong.
Asia Pacific Emerges as a High-Growth Regional Market
Asia Pacific is projected to register the highest growth rate in the global data center chip market during the forecast period. Rapid digital transformation, increasing investments in data center infrastructure, growing semiconductor manufacturing capabilities, and rising adoption of cloud computing are supporting regional expansion.
Countries such as China, Japan, South Korea, and India are strengthening their digital infrastructure and semiconductor ecosystems. Growing demand for AI applications, cloud services, and high-performance computing is creating opportunities for chip manufacturers and technology providers across the region.
Government initiatives focused on domestic semiconductor production and digital infrastructure development are also supporting market opportunities.
The expansion of regional data centers and increasing investments in AI infrastructure are expected to strengthen Asia Pacific’s position in the global market.
Competitive Landscape and Key Market Players
The global data center chip market is characterized by intense competition, technological innovation, strategic partnerships, and continuous investment in semiconductor research and development.
Major companies operating in the market include:
- NVIDIA Corporation
- Advanced Micro Devices, Inc. (AMD)
- Intel Corporation
- Samsung Electronics
- SK Hynix Inc.
- Amazon Web Services
- Micron Technology, Inc.
- Microsoft
- Texas Instruments Incorporated
- Analog Devices, Inc.
- Monolithic Power Systems, Inc.
- Altera Corporation
- Graphcore
These companies are focusing on developing advanced GPUs, AI accelerators, high-performance processors, memory solutions, and energy-efficient semiconductor technologies.
Strategic investments in customized chips, advanced packaging, high-bandwidth memory, and AI-focused computing platforms are expected to remain important competitive strategies.
Market Challenges and Emerging Opportunities
Despite strong growth prospects, the data center chip industry faces several challenges, including high development costs, limited availability of advanced GPUs, semiconductor supply chain constraints, and increasing energy consumption.
The concentration of advanced semiconductor manufacturing capacity also creates supply chain risks for manufacturers and data center operators.
However, emerging opportunities in sovereign AI infrastructure, customized accelerators, FPGA technologies, and energy-efficient computing are creating new avenues for industry expansion.
Governments and enterprises are increasingly investing in localized AI infrastructure to strengthen data security, regulatory compliance, and technological independence. These investments are expected to increase demand for advanced processors, memory technologies, and specialized AI chips.
The global data center chip market is entering a significant growth phase as AI adoption, cloud computing expansion, and high-performance computing requirements reshape semiconductor demand.
The latest Data Center Chip Market Trends highlight the growing importance of GPUs, AI accelerators, high-bandwidth memory, custom processors, and energy-efficient chip architectures.
With the market projected to reach USD 687.65 billion by 2032, semiconductor manufacturers and technology providers have substantial opportunities to capitalize on increasing investments in AI infrastructure and hyperscale data centers. Continued innovation in processing technologies, memory solutions, and customized semiconductor designs will remain essential to the industry’s long-term development.
AI Infrastructure, Cloud Computing, and High-Performance Processing Drive Market Expansion
The global data center chip industry is experiencing rapid growth as organizations increasingly invest in artificial intelligence (AI), cloud computing, machine learning, and high-performance computing infrastructure. The growing adoption of generative AI applications, large language models (LLMs), and data-intensive workloads is creating significant demand for advanced processors, graphics processing units (GPUs), memory chips, and specialized AI accelerators.
According to MarketsandMarkets, the global data center chip market is projected to grow from USD 283.16 billion in 2026 to USD 687.65 billion by 2032, registering a compound annual growth rate (CAGR) of 15.9% during 2026–2032. Increasing investments in hyperscale data centers, rising demand for energy-efficient computing, and the expansion of AI-driven applications are among the major factors supporting market growth.
The evolving Data Center Chip Market Trends indicate that semiconductor innovation, advanced processing architectures, and growing investments in AI infrastructure will play an important role in shaping the industry’s future.
Rising AI Workloads Accelerate Demand for GPUs and AI Accelerators
One of the most significant Data Center Chip Market Trends is the increasing deployment of GPUs and specialized AI accelerators to support complex computing workloads. Unlike traditional processors, GPUs are designed to handle parallel processing tasks efficiently, making them suitable for AI model training, deep learning, data analytics, and generative AI applications.
The growing use of large language models and generative AI platforms is increasing demand for high-performance computing infrastructure. Hyperscale cloud providers and enterprise organizations are investing in advanced GPU-based servers to improve processing capabilities, reduce computation time, and support large-scale AI deployments.
Specialized AI accelerators are also gaining traction because they are designed to optimize specific machine learning and inference workloads. These chips help data center operators improve computational efficiency while addressing the growing performance requirements of modern AI applications.
Hyperscale Data Center Expansion Supports Market Growth
The rapid expansion of hyperscale data centers is another important factor influencing Data Center Chip Market Trends. Cloud service providers are continuously expanding their infrastructure to accommodate increasing demand for cloud storage, enterprise applications, AI computing, and digital services.
Large data centers require advanced CPUs, GPUs, memory components, and networking chips to manage substantial volumes of information and complex computing operations.
The expansion of hyperscale infrastructure is encouraging semiconductor manufacturers to develop next-generation chips offering higher processing performance, improved scalability, and better energy efficiency.
Additionally, investments in high-speed connectivity and advanced server architectures are increasing demand for specialized semiconductor components across modern data center environments.
Growing Adoption of High-Bandwidth Memory and Advanced Semiconductor Technologies
Memory technology is becoming increasingly important as AI applications require faster access to large volumes of data. High-bandwidth memory (HBM) is gaining importance in AI servers and GPU-based computing systems because it supports high data-transfer rates and improves processing efficiency.
According to MarketsandMarkets, the memory segment is expected to register the highest CAGR of 16.7% during the forecast period.
The increasing complexity of AI models and the growing size of training datasets are encouraging manufacturers to invest in advanced memory technologies. HBM, high-speed memory interfaces, and innovative chip packaging solutions are becoming important components of next-generation data center infrastructure.
These developments are creating new opportunities for semiconductor manufacturers specializing in memory chips, advanced packaging, and high-performance computing components.
Custom AI Chips and FPGA Accelerators Create New Opportunities
Another emerging development shaping Data Center Chip Market Trends is the growing adoption of custom-designed processors and field-programmable gate arrays (FPGAs).
Cloud service providers and large enterprises are increasingly exploring customized chips to optimize computing performance for specific workloads. Application-specific integrated circuits (ASICs) and FPGAs can help organizations improve processing efficiency, reduce latency, and optimize power consumption for selected AI and data processing applications.
Custom AI accelerators are also enabling technology companies to reduce dependence on general-purpose processors for specialized computing requirements.
The growing adoption of customized semiconductor architectures is expected to create opportunities for chip developers and data center technology providers.
Energy Efficiency Becomes a Critical Market Priority
Although demand for advanced data center chips continues to increase, energy consumption remains a major industry challenge. AI training and inference workloads require substantial computing resources, increasing electricity consumption and cooling requirements across data center facilities.
As a result, manufacturers are prioritizing the development of energy-efficient processors, optimized chip architectures, and advanced power management technologies.
Innovations in semiconductor design are helping data center operators improve performance per watt while managing operational costs. Efficient memory systems, advanced packaging, and optimized computing architectures are also supporting efforts to reduce energy requirements.
The growing emphasis on sustainable digital infrastructure is expected to influence future Data Center Chip Market Trends and product development strategies.
Cloud Service Providers Lead Data Center Chip Adoption
Cloud service providers represent a major end-user segment in the global data center chip market. Companies operating large cloud infrastructure platforms require high-performance semiconductor solutions to support enterprise computing, AI services, data storage, and large-scale digital applications.
The increasing adoption of cloud-based AI platforms is encouraging providers to invest in advanced CPUs, GPUs, memory technologies, and networking components.
Technology companies are also developing proprietary processors and AI accelerators to improve infrastructure performance and optimize operating costs.
As businesses increasingly migrate workloads to cloud environments, demand for scalable and energy-efficient data center chips is expected to remain strong.
Asia Pacific Emerges as a High-Growth Regional Market
Asia Pacific is projected to register the highest growth rate in the global data center chip market during the forecast period. Rapid digital transformation, increasing investments in data center infrastructure, growing semiconductor manufacturing capabilities, and rising adoption of cloud computing are supporting regional expansion.
Countries such as China, Japan, South Korea, and India are strengthening their digital infrastructure and semiconductor ecosystems. Growing demand for AI applications, cloud services, and high-performance computing is creating opportunities for chip manufacturers and technology providers across the region.
Government initiatives focused on domestic semiconductor production and digital infrastructure development are also supporting market opportunities.
The expansion of regional data centers and increasing investments in AI infrastructure are expected to strengthen Asia Pacific’s position in the global market.
Competitive Landscape and Key Market Players
The global data center chip market is characterized by intense competition, technological innovation, strategic partnerships, and continuous investment in semiconductor research and development.
Major companies operating in the market include:
- NVIDIA Corporation
- Advanced Micro Devices, Inc. (AMD)
- Intel Corporation
- Samsung Electronics
- SK Hynix Inc.
- Amazon Web Services
- Micron Technology, Inc.
- Microsoft
- Texas Instruments Incorporated
- Analog Devices, Inc.
- Monolithic Power Systems, Inc.
- Altera Corporation
- Graphcore
These companies are focusing on developing advanced GPUs, AI accelerators, high-performance processors, memory solutions, and energy-efficient semiconductor technologies.
Strategic investments in customized chips, advanced packaging, high-bandwidth memory, and AI-focused computing platforms are expected to remain important competitive strategies.
Market Challenges and Emerging Opportunities
Despite strong growth prospects, the data center chip industry faces several challenges, including high development costs, limited availability of advanced GPUs, semiconductor supply chain constraints, and increasing energy consumption.
The concentration of advanced semiconductor manufacturing capacity also creates supply chain risks for manufacturers and data center operators.
However, emerging opportunities in sovereign AI infrastructure, customized accelerators, FPGA technologies, and energy-efficient computing are creating new avenues for industry expansion.
Governments and enterprises are increasingly investing in localized AI infrastructure to strengthen data security, regulatory compliance, and technological independence. These investments are expected to increase demand for advanced processors, memory technologies, and specialized AI chips.
The global data center chip market is entering a significant growth phase as AI adoption, cloud computing expansion, and high-performance computing requirements reshape semiconductor demand.
The latest Data Center Chip Market Trends highlight the growing importance of GPUs, AI accelerators, high-bandwidth memory, custom processors, and energy-efficient chip architectures.
With the market projected to reach USD 687.65 billion by 2032, semiconductor manufacturers and technology providers have substantial opportunities to capitalize on increasing investments in AI infrastructure and hyperscale data centers. Continued innovation in processing technologies, memory solutions, and customized semiconductor designs will remain essential to the industry’s long-term development.
Frequently Asked Questions (FAQs)
Q1. What is the expected growth of the Data Center PDU Market by 2032?
The Data Center PDU Market is projected to reach USD 14.23 billion by 2032, growing from USD 4.89 billion in 2026 at a CAGR of 19.5%.
Q2. What are the major trends shaping the Data Center PDU Market?
Major trends include AI-powered power monitoring, intelligent rack PDUs, remote power management, three-phase power distribution, DCIM integration, and energy-efficient infrastructure.
Q3. Which product segment holds the largest share of the Data Center PDU Market?
Rack PDUs hold the largest market share, accounting for 62.0% in 2025, driven by increasing demand for rack-level power distribution and monitoring.
Q4. Which region is expected to witness the highest growth in the Data Center PDU Market?
Asia Pacific is expected to experience the highest growth, registering a CAGR of 21.9% during 2026–2032 due to increasing data center investments and cloud computing adoption.
Q5. Who are the key players operating in the Data Center PDU Market?
Key players include Schneider Electric, Eaton, Vertiv, Legrand, ABB, nVent, Rittal, Delta Electronics, CyberPower, and ATEN International.
About MarketsandMarkets™
MarketsandMarkets™ has been recognized as one of America’s Best Management Consulting Firms by Forbes, as per their recent report.
MarketsandMarkets™ is a blue ocean alternative in growth consulting and program management, leveraging a man-machine offering to drive supernormal growth for progressive organizations in the B2B space. With the widest lens on emerging technologies, we are proficient in co-creating supernormal growth for clients across the globe.
Today, 80% of Fortune 2000 companies rely on MarketsandMarkets, and 90 of the top 100 companies in each sector trust us to accelerate their revenue growth. With a global clientele of over 13,000 organizations, we help businesses thrive in a disruptive ecosystem.
The B2B economy is witnessing the emergence of $25 trillion in new revenue streams that are replacing existing ones within this decade. We work with clients on growth programs, helping them monetize this $25 trillion opportunity through our service lines – TAM Expansion, Go-to-Market (GTM) Strategy to Execution, Market Share Gain, Account Enablement, and Thought Leadership Marketing.
Built on the ‘GIVE Growth’ principle, we collaborate with several Forbes Global 2000 B2B companies to keep them future-ready. Our insights and strategies are powered by industry experts, cutting-edge AI, and our Market Intelligence Cloud, KnowledgeStore™, which integrates research and provides ecosystem-wide visibility into revenue shifts.
To find out more, visit www.MarketsandMarkets™.com or follow us on Twitter , LinkedIn and Facebook .
Contact:
Mr. Rohan Salgarkar
MarketsandMarkets™ INC.
1615 South Congress Ave.
Suite 103, Delray Beach, FL 33445
USA: +1-888-600-6441
